

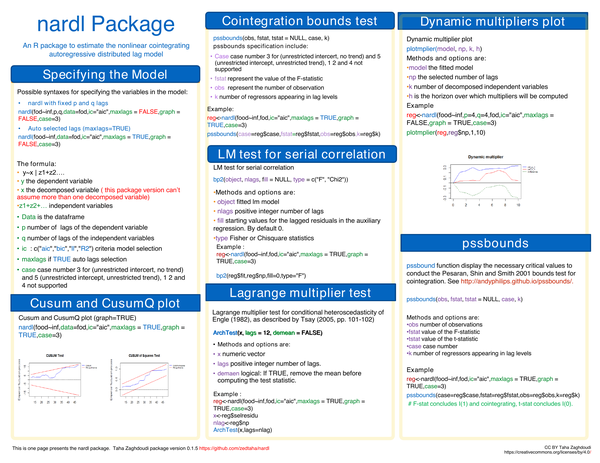
The nardl package fits nonlinear autoregressive distributed lag (NARDL) cointegration models in R, supporting automatic or fixed lag selection via information criteria. It provides Cusum and CusumQ stability plots, Pesaran-Shin-Smith bounds tests, serial correlation tests, and dynamic multiplier plots for asymmetric long-run relationships.
What’s covered#
- Specifying the model –
nardl()with fixed (p,q) or automatic (maxlags = TRUE) lag selection - Cusum and CusumQ plot – parameter stability visualization with
graph = TRUE - Cointegration bounds test –
pssbounds()with Pesaran, Shin & Smith (2001) critical values - LM test for serial correlation –
bp2()Breusch-Pagan test - Lagrange multiplier test –
ArchTest()for ARCH conditional heteroscedasticity (Engle 1982) - Dynamic multipliers plot –
plotmplier()for short- and long-run multiplier visualization